Borders Bear the Brunt: State Environmental Review and Severed Agglomerations
Matt Gustafson, Lubo Litov, and Bharat Raj Parajuli
The Pennsylvania State University, Oklahoma University, and Monash University
Abstract
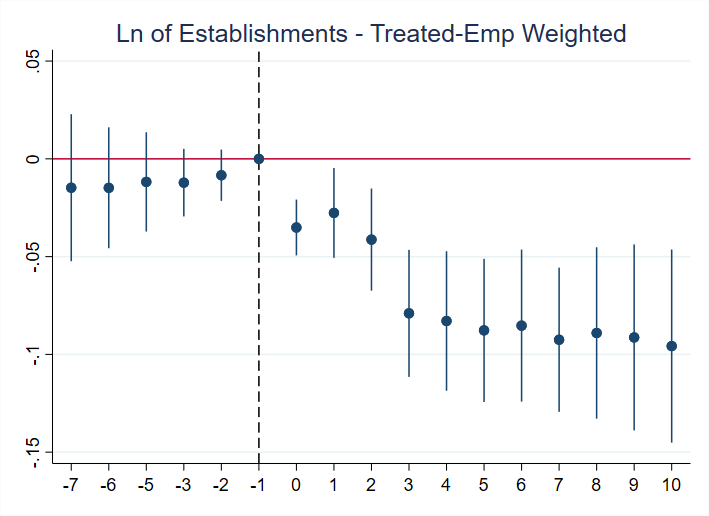
We study how state environmental review laws (SEPAs) shape local business activity. Using a stacked, border-pair event design around staggered SEPAs, we compare adjacent counties on either side of state lines. SEPA-side border counties experience slower post-adoption establishment and employment growth that cumulates into persistent level losses over two decades, with no mirror-image gains across the border and no broad underperformance in state interiors. Effects are strongest for SEPA-treated counties that border large metro areas or counties with substantial financial industries as well as when SEPAs have more economic bite. The SEPA-induced reduction in business growth falls most on pollution-intensive sectors and entirely among small firms. Overall, our findings suggest that local environmental regulations can erode local agglomerations, adversely affecting local small business growth.
Presentations: SFS Cavalcade North America, University of Virginia 2026; American Law and Economics Association Annual Meeting, University of Chicago 2026; Conference on Empirical Legal Studies, Northwestern University 2026 (scheduled); Financial Management Association Annual Meeting 2026 (scheduled); American Finance Association 2027 (scheduled); Paris School of Business; University of Tulsa; Sofia University; Oklahoma State University; University of Richmond (scheduled); Iowa State University (scheduled)
Weaponized Salience: Firm-Initiated Stock Promotions and the Failure of Mandatory Disclosure
Jonathan Brogaard and Bharat Raj Parajuli
University of Utah – David Eccles School of Business and Monash University
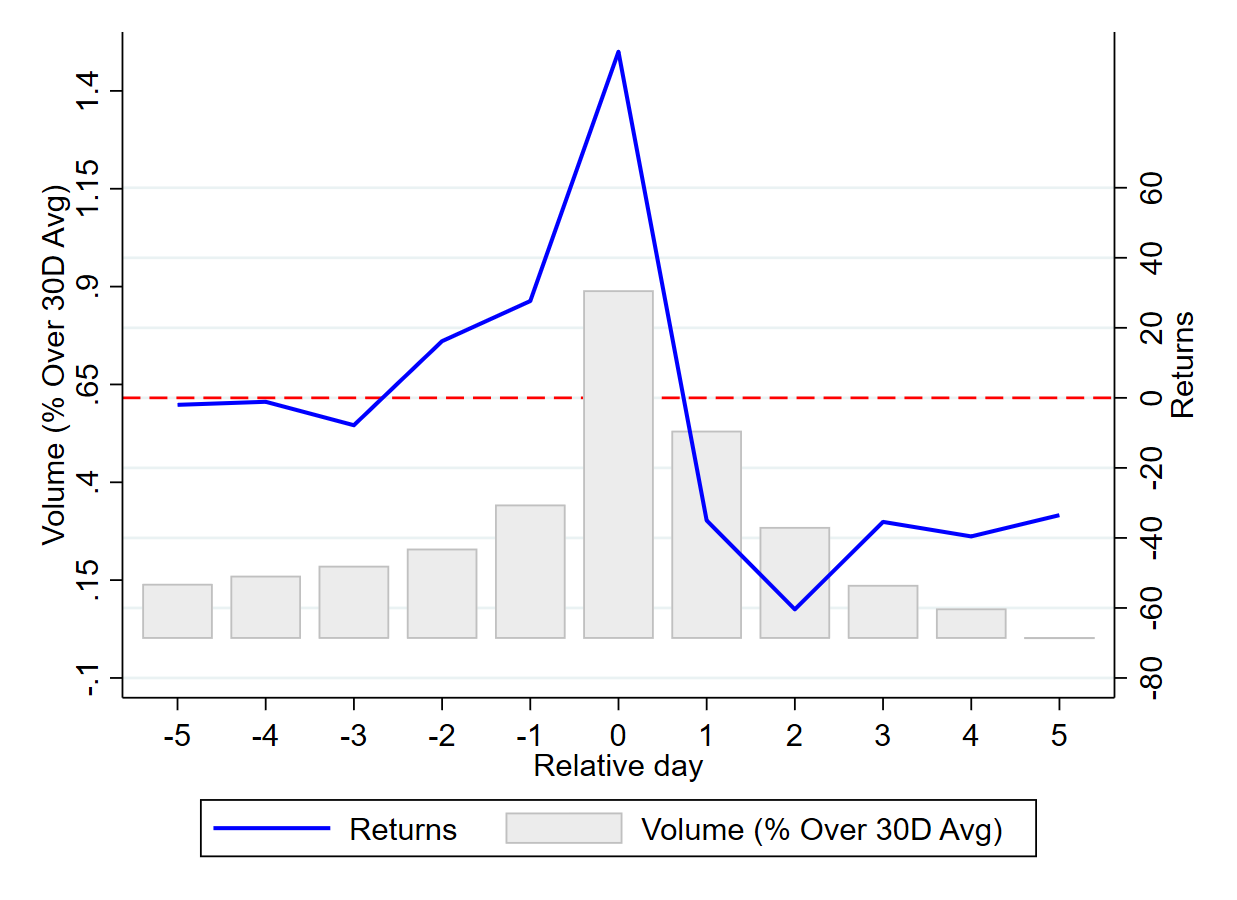
Draft coming soon.
Presentations:
Presentations: 3rd Financial Fraud, Misconduct and Market Manipulation Conference 2026
ESG Everywhere
Bharat Raj Parajuli, Michael J. Cooper and Michael Halling
Monash University, University of Utah – David Eccles School of Business and University of Luxembourg
Abstract
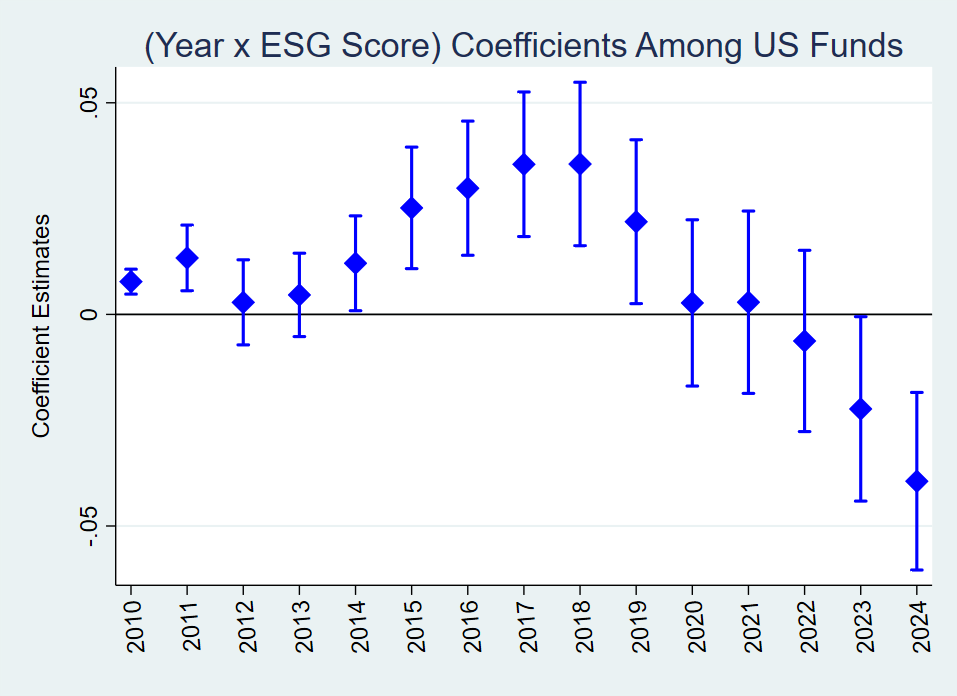
Our findings reveal that ESG is everywhere in mutual fund investment decisions-playing an important role not only for ESG-designated funds but across all categories of mutual funds-ranking ahead of traditional factors such as momentum and book-to-market ratios. Surprisingly, ESG scores matter for all funds even in the most recent data, a period of arguably anti-ESG sentiment. We find that ESG scores have an even greater impact in brown industries, such as oil and gas, than in non-brown industries and for mutual fund managers with Democratic party leanings. These results highlight the evolving priorities of mutual fund managers, with ESG considerations increasingly integrated into investment strategies alongside traditional risk-return metrics.
Presentations:
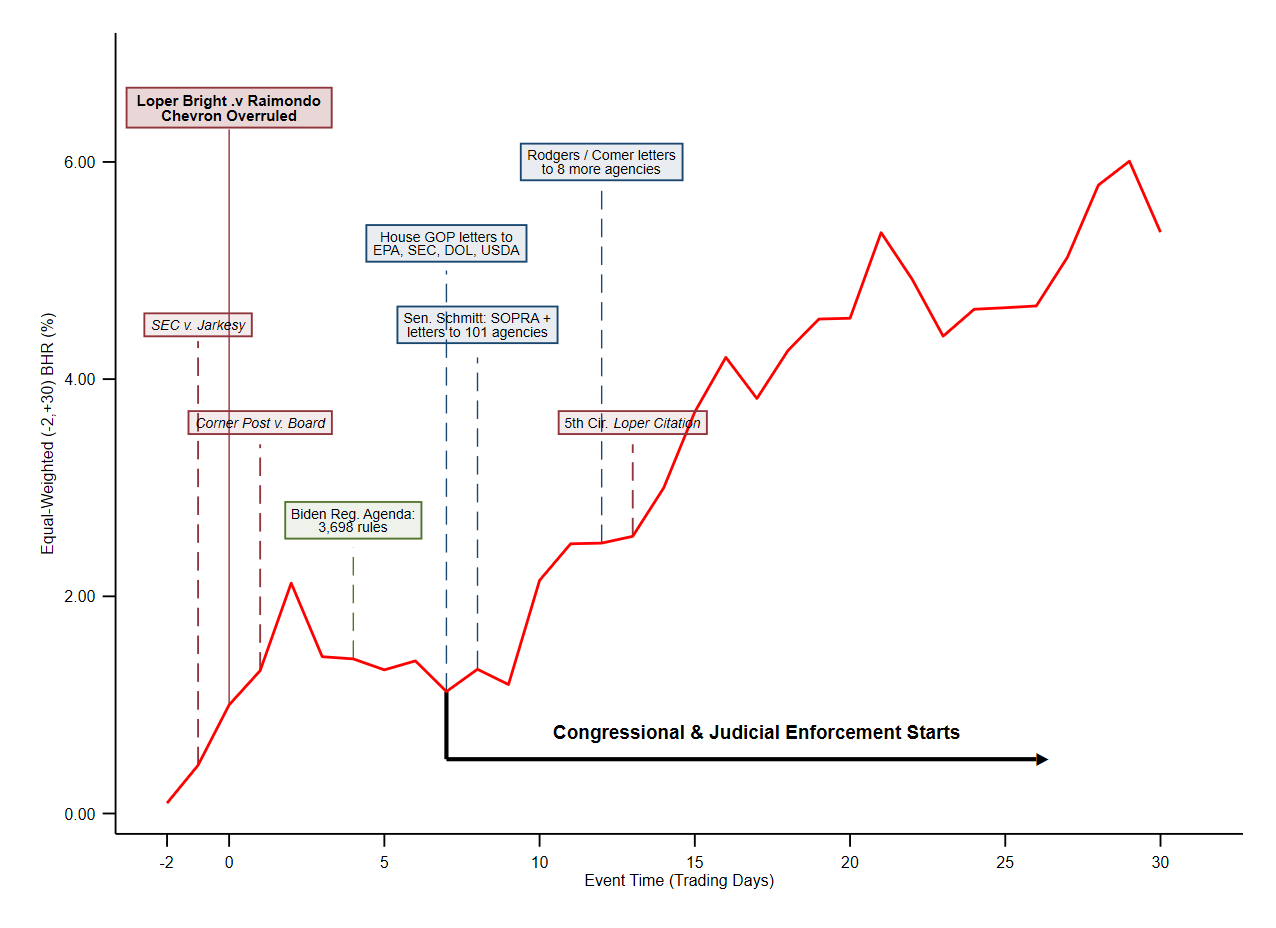
Costly Rules, Uncertain Courts: Wealth Redistribution from the Rise and Fall of Chevron Deference
Phong T. H. Ngo, Bharat Raj Parajuli, and Tom Smith
Australian National University, Monash University, and Macquarie University
Abstract
We examine how financial markets value regulation versus courts as enforcement mechanisms for property rights by exploiting the Supreme Court’s 2024 reversal of Chevron deference (CD). We find wealth is redistributed from small firms to larger firms, consistent with larger firms possessing an advantage in courts due to their greater financial resources. Higher judicial uncertainty for small firms can explain most of the reduction in small firm value. These effects are amplified in districts with congested or ideologically imbalanced courts and reverse cleanly in 1984 when CD was first introduced, providing a forty-year mirror image. Our results highlight a trade-off between costly regulatory (ex-ante) versus uncertain judicial (ex-post) enforcement.
Presentations: Conference on Empirical Legal Studies, Northwestern University 2026 (scheduled); Financial Management Association Annual Meeting 2026 (scheduled); Australasian Banking and Finance Conference 2026 (scheduled); New Zealand Finance Meeting 2026 (scheduled); University of Southampton
Reserve, Risk-Tolerance, and Fund Flows
John C. Chu and Woon Sau Leung
Monash University and University of Southampton Business School
Draft coming soon.
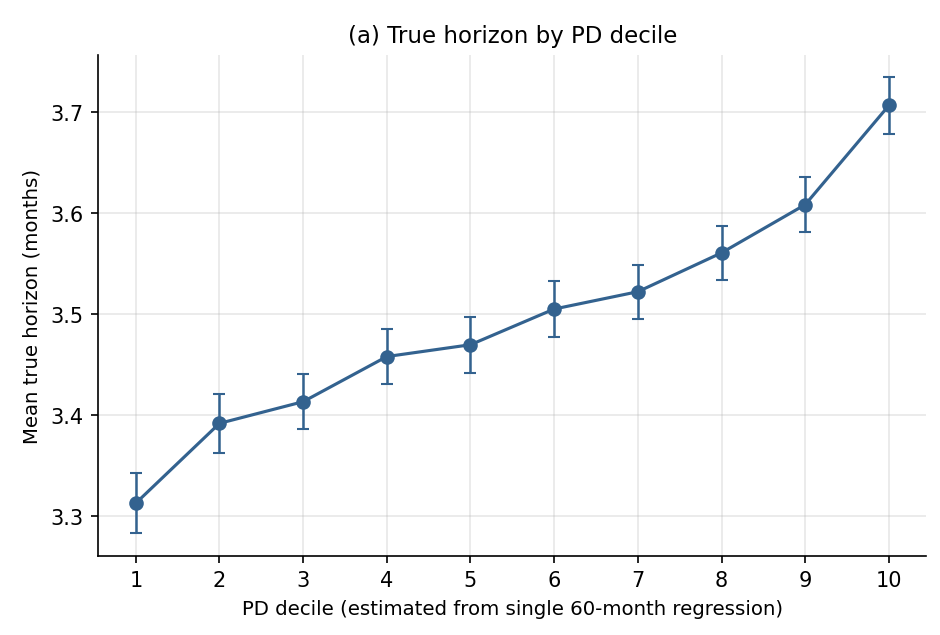
Two Frictions, Two Legs: The Distinct Roles of Information Diffusion and Arbitrage Risk in Anomaly Returns
Monash University
Abstract
Whether anomalies reflect limits to arbitrage or information frictions is unresolved, in part because the two are difficult to separate empirically. I exploit anomalies’ long and short legs, where only short selling faces binding constraints. A new firm-specific delay measure, PD, and idiosyncratic volatility (IVOL) moderate a composite anomaly signal. Information frictions amplify the anomaly only on the long leg; arbitrage risk moderates it symmetrically on both. On the long leg, PD and IVOL are complements, mattering only jointly; on the short leg they decouple, IVOL acting alone. PD is a pure moderator, not priced on its own, and survives extensive controls.
Presentations: European Financial Management Association 2025; Sydney Banking and Financial Stability Conference 2025; Australasian Banking and Finance Conference 2026 (scheduled)
Abstract
This paper shows that momentum profits concentrate among firms with high firm-specific price delay (PD), a firm-level measure of information friction. Theories of momentum attribute return continuation to the gradual incorporation of firm-specific information, yet direct empirical support has been elusive. Using the firm-specific price-delay measure of Parajuli (2025), I show that momentum is a conditional phenomenon: in Fama–MacBeth regressions, the interaction between PD and past returns subsumes the significance of past returns alone, so that momentum is strong among high-PD firms and absent among low-PD firms. The result strengthens under value-weighting and the exclusion of microcaps, and is robust to idiosyncratic volatility, transaction costs, illiquidity, existing price-delay measures, and other documented momentum drivers. It holds across ninety-one markets and survives an extensive battery of tests against a mechanical interpretation. By locating momentum in a measure of firm-specific price discovery, the findings provide direct empirical support for information-based theories of momentum.
Presentations: Academy of Behavioral Finance & Economics 2019; Behavioral Finance and Capital Markets 2019; Financial Management & Accounting Research Conference 2022; Financial Management Association Europe 2022; FIRN Asset Management Conference 2024; Australasian Banking and Finance Conference 2025
Abstract
I motivate and find empirical evidence that positive information is more valuable to investors than negative information. Post corporate under-(over-)valuation signals, information production increases (decreases), increasing (decreasing) price informativeness (PI). PI decreases more in firms with worse investment opportunities, poor corporate governance, more entrenched manager, and higher short-sale constraints. And, PI increases more in firms with better investment opportunities and higher investment-to-Q ratios. Results imply that market over-valuations are corrected slower than under-valuations and hence are stickier and more prevalent in the economy. Persistent and long-lasting performances of short-legs of anomaly portfolios could be the result of such a phenomenon.
Presentations: American Finance Association Conference (PhD Poster Session) 2021; Western Economic Association International 2023; Financial Management Association Europe 2024; Financial Management Association Annual Meeting 2024; Australasian Banking and Finance Conference 2024; Sydney Banking and Stability Conference 2024; Southwestern Finance Association 2025
Work in Progress
Early-stage projects, not yet available as drafts
Source of Credit and Capital Efficiency
Si Cheng (Syracuse University) and Massimo Massa (INSEAD and Singapore Management University)
Anti- and Pro-ESG Laws
Mike Cooper, Fan Li (St. John Fisher University), and Jixing Li (New Jersey Institute of Technology)